UK Share Investors: HMRC Tax Rules for Capital Gains, ERI, Dividends and Interest
For UK private investors holding shares, ETFs, investment trusts or funds outside an ISA or SIPP, tax reporting can become increasingly complex—especially when you start selling investments, receiving dividends or holding offshore reporting funds.
UK HMRC Shares and Capital Gains Tax helpsheet HS284
This guide covers:
- Capital Gains Tax (CGT) annual allowances
- CGT tax rates
- Excess Reported Income (ERI) on offshore ETFs/funds
- Dividends and broker tax reports
- Interest on cash
- CFDs
1. Capital Gains Tax (CGT) Annual Allowance
UK private individuals receive an Annual Exempt Amount (AEA) for capital gains. This is the amount of gains you can make in a tax year before CGT becomes payable.
For share investors, this applies to gains from:
- Individual shares
- ETFs
- Investment trusts
- Unit trusts and OEICs
- Offshore reporting funds
Official HMRC guidance:
HMRC Capital Gains Tax rates and allowances
HMRC reference: SA108 Capital Gains Tax summary form and notes.
HMRC UK Capital Gains share matching rules
The order of priority for matching share buys to share sells (including FIFO)
- Same-Day Rule
- Shares sold are matched first against any shares of the same class acquired on the exact same calendar day.
- 30-Day Rule (Bed & Breakfasting) with FIFO
- Remaining sold shares are matched against acquisitions made within the 30 calendar days following the day of disposal.
- The FIFO Rule: If you make multiple purchases within this 30-day window, matching occurs chronologically. The earliest purchase inside the window is matched first until exhausted, before moving to the next chronological purchase.
- Section 104 Pool
- Any remaining sold shares that cannot be matched by steps 1 or 2 are matched against the average cost of the Section 104 Pool (the collective pool of all shares held prior to the day of sale).
CGT Annual Allowance (Private Individuals)
| Tax Year | Annual CGT Allowance |
|---|---|
| 2016/17 | £11,100 |
| 2017/18 | £11,300 |
| 2018/19 | £11,700 |
| 2019/20 | £12,000 |
| 2020/21 | £12,300 |
| 2021/22 | £12,300 |
| 2022/23 | £12,300 |
| 2023/24 | £6,000 |
| 2024/25 | £3,000 |
| 2025/26 | £3,000 |
After several years of stability, the allowance was significantly reduced from April 2023 onward.
2. Capital Gains Tax Rates on Shares
For most share disposals, CGT depends on whether your taxable income keeps you in the basic-rate band or higher-rate band.
CGT Rates for Shares, ETFs and Funds
| Tax Year | Basic Rate Taxpayer | Higher Rate Taxpayer | Notes |
|---|---|---|---|
| 2021/22 | 10% | 20% | Standard rates |
| 2022/23 | 10% | 20% | Standard rates |
| 2023/24 | 10% | 20% | Standard rates |
| 2024/25 (6 Apr–29 Oct) | 10% | 20% | Before October Budget |
| 2024/25 (30 Oct–5 Apr) | 18% | 24% | After October Budget |
| 2025/26 | 18% | 24% | Current |
When calculating your CGT, you first deduct:
- Allowable purchase cost
- Trading costs (where allowable)
- Any previous ERI already taxed for the shares sold (if applicable)
- Annual CGT allowance (from total)
The remaining gain is then taxed at the appropriate rate by HMRC.
3. ERI (Excess Reported Income)
Many ETFs (both distributing and accumulating) available to UK investors are offshore funds with UK reporting fund status, commonly domiciled in:
- Ireland (ISIN begins with IE)
- Luxembourg (ISIN begins with LU)
Examples include ETFs from:
- Vanguard
- BlackRock
- Invesco
- and many more
These funds may retain income inside the fund rather than paying it out. That retained taxable income is called Excess Reported Income (ERI).
Note that UK law states that you should declare ERI even if it has been earned within an Accumulating ETF/Fund and not paid out directly to you. For this reason Accumulating offshore reportable ETFs (i.e. most accumulating ETFs) are usually avoided by UK investors. Instead, Distributing ETFs are typically held in GIAs – although even some of these may declare a small ERI each year.
For most equity ETFs, ERI is usually treated as a notional overseas dividend for UK tax purposes.
However, ERI is not always dividend income. Some funds—particularly money market or cash-like funds—may classify the reportable income as an amount treated in the same way as interest for UK tax purposes, rather than dividend income. These amounts are still subject to income tax, but under interest rules rather than dividend rules.
So investors should always check the ETF’s Reportable Income document to confirm the exact tax treatment.
HMRC Reporting Funds List
HMRC publishes the official list of reporting funds here:
HMRC Offshore Funds List of Reporting Funds
This lets you verify:
- Whether your ETF had reporting fund status (lookup the ISIN)
- The dates reporting status applied to your particular share
Key ERI Dates
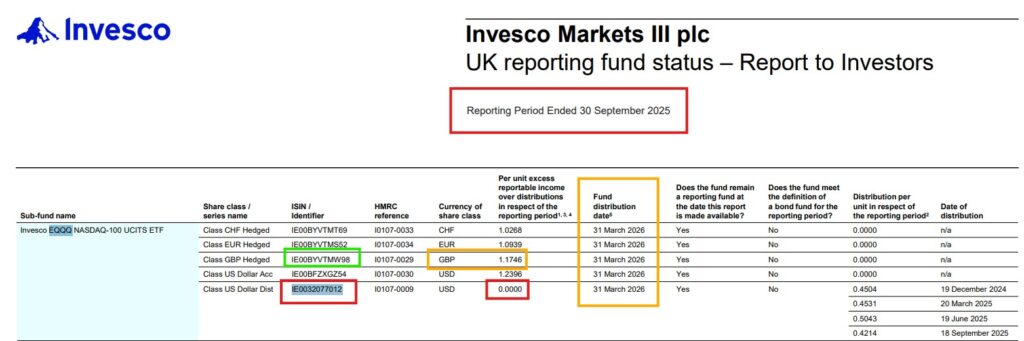
1. Reporting Period End Date
This is the ETF’s accounting year-end.
Example:
31 December 2025
If you held the ETF on this date, ERI may apply to you if ERI for that tax year is reported as > 0. If the reportable offshore fund ISIN was not held on that one day, then ERI for the tax year for that Reporting Date does not apply. This means only capital gain on sale and any paid dividends need to be declared for that tax year.
2. Fund Distribution Date
This is normally 6 months after the reporting period end.
Example:
Reporting period end = 31 Dec 2025
Distribution date = 30 Jun 2026
This is normally when the ERI becomes taxable for UK investors. It a notional distribution which you received on the distribution date (even if you no longer hold those shares).
Distributing vs Accumulating ETFs
A practical point many UK investors discover:
Distributing ETFs (“Dist”)
Distributing ETFs physically pay out their dividends.
Because the income has already been distributed, many distributing ETFs often report zero ERI or only a very small ERI in most years. For example WITS is a distributing world tech ETF which as an ERI of 0 for most years, but had an ERI of 0.0004 on the reporting date of 30/11/2025.
Accumulating ETFs (“Acc”)
Accumulating ETFs reinvest income inside the fund.
Because income is retained rather than paid out, accumulating ETFs often generate some notional ERI each year.
This creates additional tax administration in a General Investment Account (GIA), because:
- ERI may need declaring each year even though no cash was received
- ERI records must be kept for future CGT adjustments
For this reason, many UK investors prefer to hold distributing ETFs rather than accumulating ETFs in a GIA, because distributing ETFs often result in little or no ERI reporting.
Accumulating ETFs are often simpler inside ISAs or SIPPs, where ERI reporting is generally irrelevant.
Here are the ERI income figures over several years for 100 shares of XLKW (acc), EQQQ (dist) and WITS (dist)
DIVIDEND 30/09/2021 EQQQ 100.000 0.00
DIVIDEND 30/11/2021 WITS 100.000 0.00
DIVIDEND 30/11/2021 XLKQ 100.000 255.88
DIVIDEND 30/09/2022 EQQQ 100.000 0.76
DIVIDEND 30/11/2022 WITS 100.000 0.00
DIVIDEND 30/11/2022 XLKQ 100.000 155.43
DIVIDEND 30/09/2023 EQQQ 100.000 0.74
DIVIDEND 30/11/2023 WITS 100.000 0.00
DIVIDEND 30/11/2023 XLKQ 100.000 343.37
DIVIDEND 30/09/2024 EQQQ 100.000 13.34
DIVIDEND 30/11/2024 WITS 100.000 0.00
DIVIDEND 30/11/2024 XLKQ 100.000 323.86
DIVIDEND 30/09/2025 EQQQ 100.000 0.00
DIVIDEND 30/11/2025 WITS 100.000 0.03
DIVIDEND 30/11/2025 XLKQ 100.000 294.75
Example: Finding ERI for EQQQ
Suppose you hold:
Invesco EQQQ NASDAQ-100 UCITS ETF (dist.)
EQQQ is a distributing fund so the ERI would be expected to be 0 or very small (e.g. $0.04 per share). There are two common ways to find the ERI amount.
Method 1 — KPMG Reporting Fund Database
KPMG hosts a searchable database of reporting fund data:
KPMG Reporting Funds Database (free sign-in required – search using the ISIN number for best results)
Tip: Most broker sites will display the ISIN number if you look up the ticker symbol.
Steps:
- Register with KPMG for free investor access
- Search for EQQQ (or the ISIN for more accurate results)
- Open the correct share class (if only a few years are shown, it usually means the ERI was 0 for the missing years)
- Review the tax report
You will usually see:
- Reporting period
- Distribution amount
- Excess Reported Income per share (for that tax year)
- Distribution date
Method 2 — Provider Website
Many ETF providers publish reporting fund documents directly on their product pages.
For example:
Steps:
- Search for Invesco EQQQ NASDAQ-100 UCITS ETF
- Open the fund’s Documents or Literature section
- Find the Reportable Income document (sometimes called Reporting Fund Report) for the appropriate tax year or accounting period
- Open that report and locate:
- Reporting period end date
- Fund distribution date (always end of the month 6 months later)
- Excess Reported Income (ERI) per share/unit
That ERI per share is the amount you multiply by the number of shares you held on the reporting period end date.
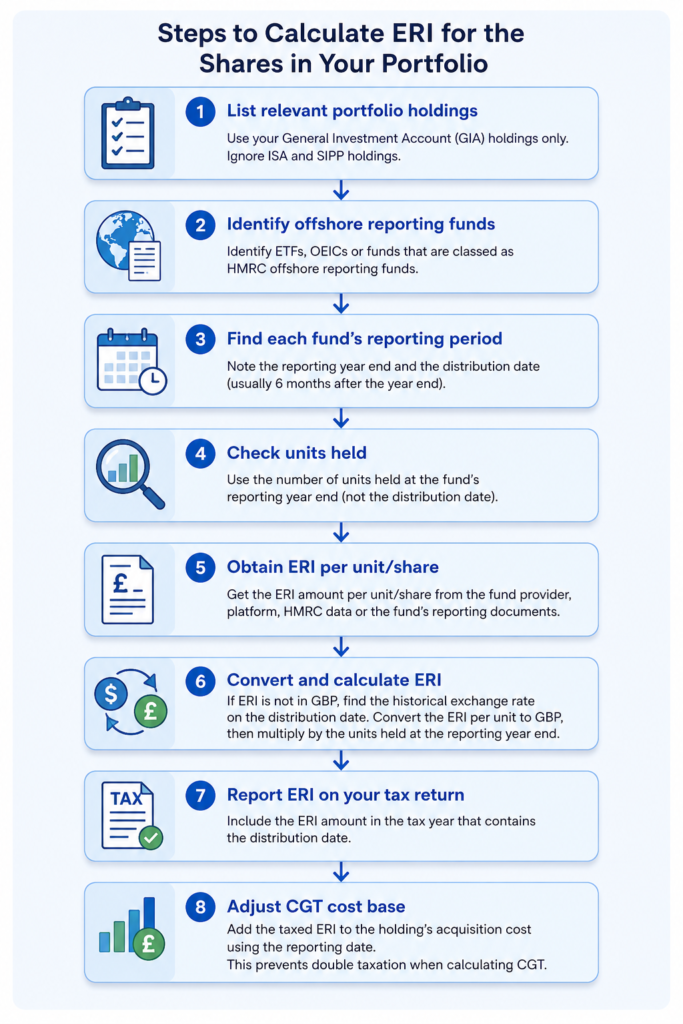
ERI Calculation Example
Suppose:
You held 200 shares of Invesco EQGB NASDAQ-100 UCITS ETF (acc) on the Reporting Period End Date.
The Reportable Income document shows:
ERI = $0.85 per share
Total ERI:
200 × $0.85 = $170
Note that the distributing ETF EQQQ may have an ERI of 0 or a small amount such as $0.04 because in most years, the dividends are paid out to share holders as separate payments.
Foreign Currency Conversion
Most offshore ETFs report ERI in a foreign currency, commonly USD or EUR.
For UK tax reporting, the ERI must be converted into GBP using the exchange rate on the Fund Distribution Date.
It is the distribution date exchange rate—not the purchase date, reporting date or sale date—that should normally be used.
HMRC exchange rates can be found here:
Example
Suppose:
ERI = $170
Distribution date = 30 June 2026
Assume the GBP conversion on that date gives:
$170 = £136
It is £136 that is declared as taxable overseas dividend income on your UK tax return (assuming the fund classifies the ERI as dividend income).
The Reporting Date Rule (Very Important)
ERI only applies if you actually held the ETF on the fund’s Reporting Period End Date.
If you did NOT hold the ETF on the Reporting Period End Date then no ERI arises for that reporting period.
That means:
- No ERI income to declare
- No ERI cost adjustment for CGT
If you sold the ETF just before the Reporting Period End Date or bought the ETF just after the Reporting Period End Date, you were not a holder on that date, so no ERI applies for that reporting period.
If you DID hold the ETF on the Reporting Period End Date
ERI applies—even if you sell the ETF the very next day.
Example:
- Reporting date = 31 Dec 2025
- You held the ETF on 31 Dec 2025
- You sold all holdings on 1 Jan 2026
ERI still applies.
You must:
- Declare the ERI on the Fund Distribution Date
- Add that ERI amount to your acquisition cost when calculating CGT on any sale
How ERI Reduces Future CGT
Once ERI has already been taxed, you can add it to your acquisition cost when you later sell the ETF.
This prevents double taxation.
Example
Original purchase cost = £10,000
ERI already taxed (over last 3 years) = £350
Sale proceeds = £15,000
Adjusted acquisition cost:
£10,000 + £350 = £10,350
Capital gain:
£15,000 − £10,350 = £4,650
Without adjusting for ERI, the gain would incorrectly be:
£15,000 − £10,000 = £5,000
So the ERI reduces the taxable gain by £350.
4. Dividends
Most brokers provide annual tax reports showing dividends received during the UK tax year.
Common brokers used by UK investors include:
- Trading 212
- Interactive Brokers
- Hargreaves Lansdown
These reports can normally be used when completing Self Assessment.
However, investors should check whether dividends are correctly split between:
UK Dividends
Examples:
- BP plc
- HSBC Holdings plc
These are normally UK dividends.
HMRC separates Dividends from UK companies (SA100 box 4 (Dividends from UK companies))
and Other dividends (box 5 (Other dividends)). Other dividends include dividend distributions from
authorised unit trusts, OEICs and investment trusts. If you need to split a UK payment between those
HMRC categories, you may need to check the type of instrument, because the Annual Statement does
not split them automatically.
HMRC reference: SA150 Notes, page TRG 7.
Overseas Dividends
This is where ETFs often cause confusion.
Most UCITS ETFs available to UK investors are domiciled in:
- Ireland
- Luxembourg
So ETF distributions from funds such as:
- Vanguard FTSE All-World UCITS ETF
- iShares Core MSCI World UCITS ETF
- Invesco EQQQ NASDAQ-100 UCITS ETF
are usually treated as overseas dividends for UK tax purposes, even if the ETF holds UK shares.
This is because the income is normally sourced from the country where the fund itself is domiciled, not from the countries of the underlying shares.
Some brokers clearly separate UK and overseas dividends. Others combine them, so investors may need to identify and separate them manually for Self Assessment.
Use the country, gross amount and foreign tax. If you complete SA106, use a separate row for each country and use the HMRC 3-letter country code. Do not rely on the net amount on its own. If you are using the main return for small amounts, HMRC uses SA100 box 6 (foreign dividends up to £500 – see notes) and box 7 (foreign tax taken off).
HMRC says that in limited cases, some small amounts of foreign interest and foreign dividends can go on the main return, but otherwise the Foreign pages are used. Check the current HMRC notes before filing.
HMRC reference: SA150 Notes, pages TRG 6 to TRG 7; SA106 Notes, pages FN 2 and FN 7.
HMRC 2026 – if your only foreign income was untaxed foreign interest up to £2,000 and or foreign dividends up to £500, you can put these amounts in box 3 and box 5 on page TR 3 of your tax return instead of completing the ‘Foreign page’ (subject to the guidance on pages TRG 5 and 6)
Distributions – Interest or Dividend?
In the case of most shares and funds, these will usually be classed as dividends.
HMRC does not treat all distributions/ERI in the same way. Depending on the fund, a payment can be interest, a dividend, property income or miscellaneous income. HMRC also says reporting funds can create excess reported income, even where cash has not been paid out. Do not map the Distribution overview to one tax return box unless the tax character is clear from HMRC guidance or the fund manager information. Check HMRC HS265 or fund manager information before choosing a return box.
HMRC reference: SA150 Notes , pages TRG 6 to TRG 7; SA106 Notes, page FN 7; HS265 Offshore funds.
ERI can be classed as dividends or income depending on the type of offshore fund. For instance the Money Market fund CSH2 is an accumulating fund which has a notional interest rate. This is a cash type fund (not investment) and so the ERI rate will be quite high and ERI should be reported as Foreign Interest (IRL) not Foreign Dividend.
5. Interest on cash
HMRC uses different boxes for UK interest and foreign interest.
● UK interest: SA100 box 1 (taxed) or box 2 (untaxed).
● Foreign interest: if your only foreign income is untaxed foreign interest up to £2,000, put it in SA100 box 3 and name the country in “Any other information”.
Otherwise, use SA106.
Check the current HMRC notes before filing.
HMRC reference: SA150 Notes, page TRG 6; SA106 Notes, pages FN 6 to FN 7.
Income generated for share lending on T212 is generally counted as interest income and so can be added to any cash interest when declaring to HMRC.
Tips
For every taxable investment account outside an ISA or SIPP, keep copies of:
- Buy and sell contract notes
- Dividend statements
- ERI / Reportable Income documents
- Broker annual tax summaries
- FX conversion records for non-GBP investments
Good records make future CGT calculations much easier—especially when multiple ERI adjustments have built up over several years.
If you have several different brokers and thus several different GIAs, you should combine all trades from all brokers into one report and then calculate your taxable gains using s cslculator that follows the HMRC rules. You should NOT simply add up the gains in each broker’s annual report. First, the broker does not apply HMRC rules, and secondly, the broker does not know what other buys and sells you made in the tax year with your other brokers. To avoid errors, each tax year, you should include all the trades that you ever made frm each broker. Many people find it easier to just use one broker that has good transaction reporting for their GIA account (there is no problem using many different brokers for your ISAs, but remember the deposit limit applies across all ISA accounts!)
Many experienced UK ETF investors find that ERI tracking is one of the most commonly overlooked parts of tax reporting.
For basic-rate taxpayers, correctly declaring ERI that is taxed as dividend income, and then adding that taxed ERI to the ETF acquisition cost when you eventually sell, can reduce your overall tax bill.
This is because dividend tax for a basic-rate taxpayer is normally lower than the current 18% Capital Gains Tax rate. By declaring the ERI as a dividend when it arises, and then adding that already-taxed ERI to the ETF acquisition cost, your eventual taxable capital gain is reduced.
In effect, some of what might otherwise have been taxed later at 18% CGT is instead taxed earlier at the lower basic-rate dividend tax rate, reducing the overall tax payable.
For many investors the saving may be modest—often only £5 to £20 per year—but over many years or across multiple ETF holdings, it can add up. If you have large holdings in your GIA of accumulating ETFs, you should pay particular attention to ERI. very few CGT calculation sites include ERI in their calculations because it is very hard to automate the ERI rate lookup!
Tips on Self Assessment form filling
Capital Gains section
You should attach PDFs to show your trades and workings. If you have more than say 6 trades, then it is best to answer ‘No’ to the question ‘Do you want to use the capital gains computation worksheet for any of your disposals?’
Tick Cryptoassets (if you sold any crypto) and Listed Shares (plus any others that apply).
Note that if you have sold shares which are unlisted or are on the AIM market, these should be treated as ‘Unlisted shares‘ for which there is a separate tax report page. The ukcgt.xyz calculator may combined unlisted AIM shares with all other listed shares if the same ticker symbol is used on multiple stock markets, so you may need to manually adjust the reported gains in the listed shares section to deduct the unlisted gains (or make appropriate adjustments). For most retail investors (where special business relief or tax benefits don’t apply) AIM shares will be taxed the same way as listed shares however and so separation will not make any/much difference. You can change the ticker symbol to tell ukcgt that it is a London share by adding .L – for instance RFX can be changed to RFX.L and it will detect that it is an AIM market share and ukcgt.xyz will give you a total for unlisted shares in the summary and not include it as a listed share.
For Cryptoassets, you can just fill in the gain or loss boxes and later attach a PDF of the transactions
For the ‘Listed shares and securities’ page, most entries are optional and you can fill in the Gains box and number of disposals.
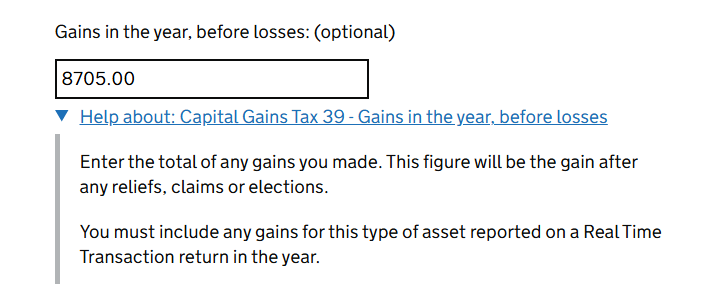
The HMRC Self-Assessment form may talk about ‘Real Time Transaction‘ returns – this refers to the ability for you to report to HMRC large capital gains transactions for listed shares as they happen or shortly afterwards as separate incidents before the end of the tax year. If you have used this service within the tax year (not many people will have used it for listed shares), then you will need to also fill in the relevant section ‘Total gains or losses on the disposal of an asset of this type reported on Real Time Transaction returns: (optional)’. If you have not used the RTT service, any references to ‘Real Time Transactions’ can be ignored.
The last page allows you to attach PDFs. These should detail the transactions and show calculations and how each trade has been identified and treated under HMRC rules. Simply attaching a broker’s tax year report alone, is usually not sufficient because 99% of these reports do not account for all HMRC rules and if you have multiple brokers, all trades should be combined before calculating gains. ukcgt.xyz allows you to download PDFs for the tax year in the calculator, and if applicable, an ERI PDF report for the tax year using the ERI_Lookup page.
6. CFDs
If you are an average retail (domestic) investor and have traded only lightly in a CFD account (not hundreds of day trades!), any gain or loss that you have made in the tax year may need to be reported to HMRC as a Capital Gain/Loss.
Typically, you can simply use the total CFD figures from your broker’s tax year annual report PDF and enter the total cost and total proceeds in the Other property, assets and gains section of the Self Assessment form (boxes 14 to 22 on the 2025/26 form).
Note that if you made a loss in the tax year you should report this, because any losses will reduce any capital gains you may have made on shares or other investments. An overall loss can be carried forward into the next tax year. Most people who try CFDs will lose money!
ukcgt.xyz does not currently support CFDs (not tested). HMRC rules also state that the same-day, 30-day and Section 104 pooling rules also apply to CFDs. Your broker’s tax year report may not take these rules into account, so if you think you may have bought the same CFD within 30 days of selling it, you may need to use a CFD calculator or employ an accountant.
Since the CGT threshold is currently £3000 (2025/2026, 2026/2027), if all your capital gains (including shares, losses, etc.) are below £3000 in the tax year, you do not need to report the gains to HMRC (but you should report within four years if you made a loss so it can be deducted from any future gains in following years). You should register if self assessment by October 6th if you total gains exceeded £3000 (contact HMRC if you have not registered in time!) – your SA must be submitted by 31st January.
NOTE: I am not a tax advisor. The information on this page is for guidance only and may not be 100% correct. It is your responsibility to ensure your calculations are correct!